
First Bancorp has been treading water for the past six months, recording a small return of 1.7% while holding steady at $59.25. The stock also fell short of the S&P 500’s 11.2% gain during that period.
Is now the time to buy First Bancorp, or should you be careful about including it in your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Is First Bancorp Not Exciting?
We don’t have much confidence in First Bancorp. Here are three reasons we avoid FBNC, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
Net interest income and fee-based revenue are the two pillars supporting bank earnings. The former captures profit from the gap between lending rates and deposit costs, while the latter encompasses charges for banking services, credit products, wealth management, and trading activities.
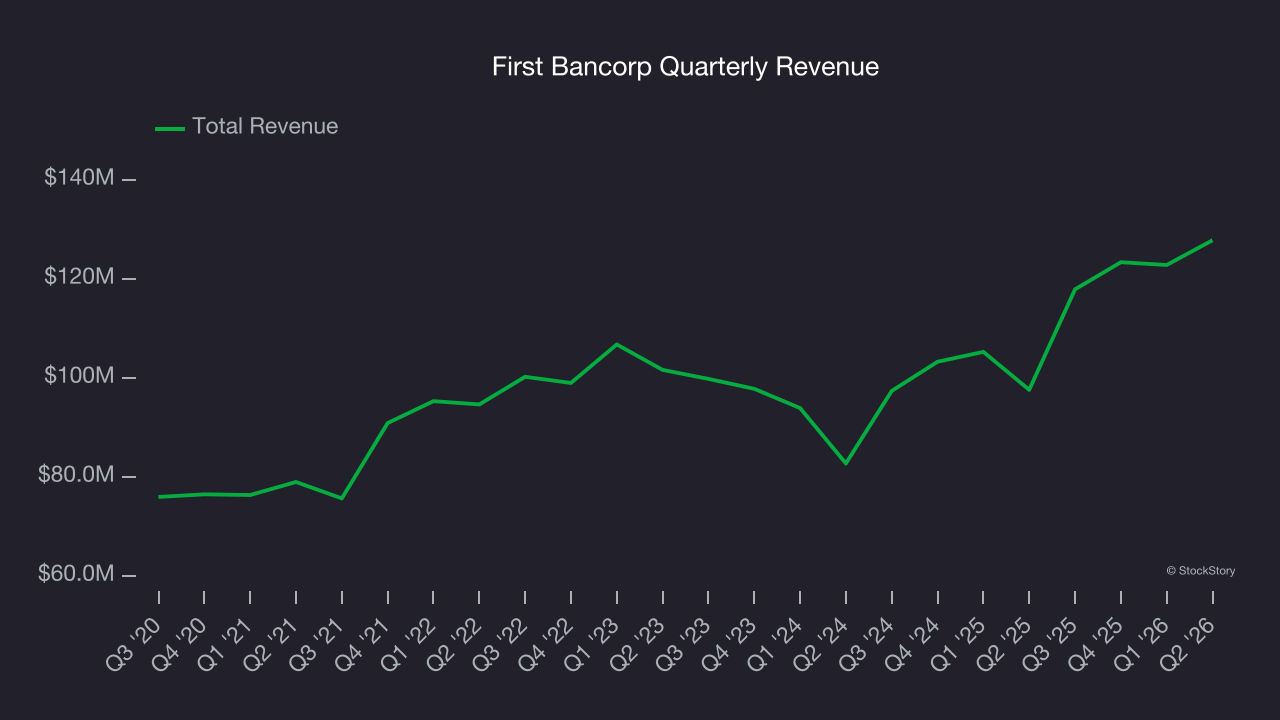
Unfortunately, First Bancorp’s 9.8% annualized revenue growth over the last five years was mediocre. This was below our standard for the banking sector.
2. EPS Barely Growing
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
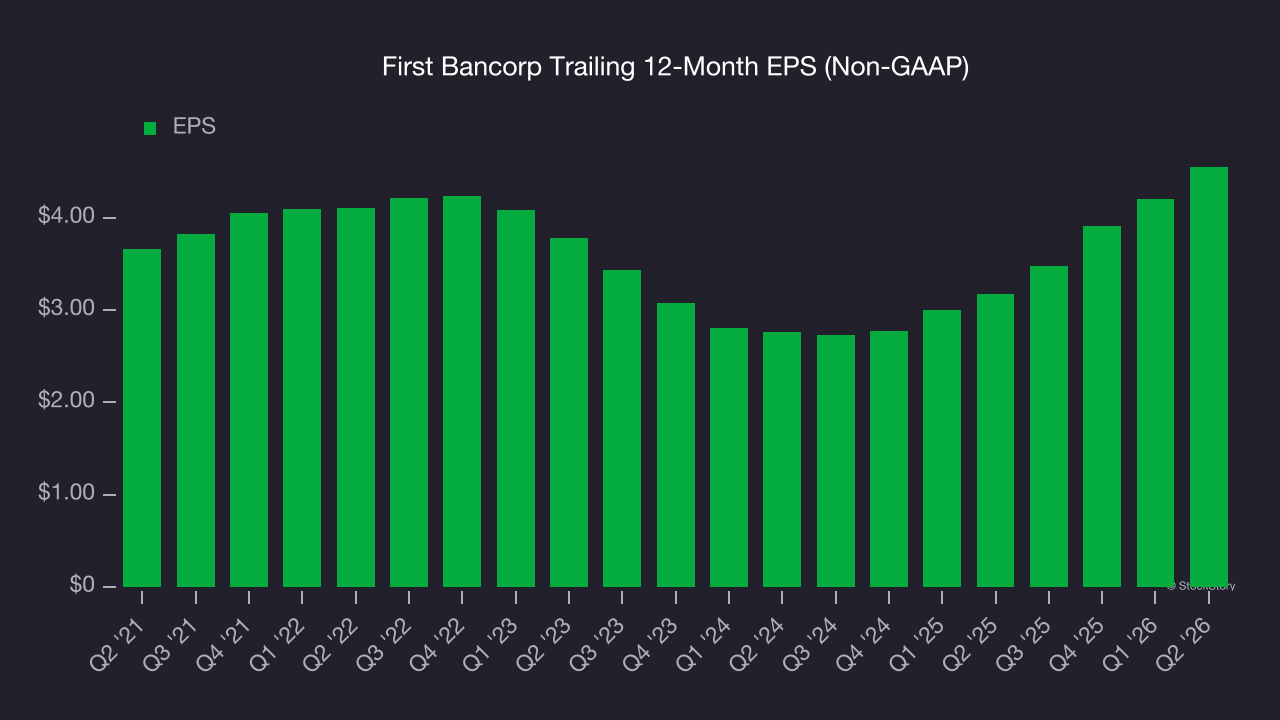
First Bancorp’s EPS grew at a weak 4.4% compounded annual growth rate over the last five years, lower than its 9.8% annualized revenue growth. This tells us the company became less profitable on a per-share basis as it expanded.
3. Previous Growth Initiatives Haven’t Impressed
Return on equity, or ROE, quantifies bank profitability relative to shareholder equity - an essential capital source for these institutions. Over extended periods, superior ROE performance drives faster shareholder wealth compounding through reinvestment, share repurchases, and dividend growth.
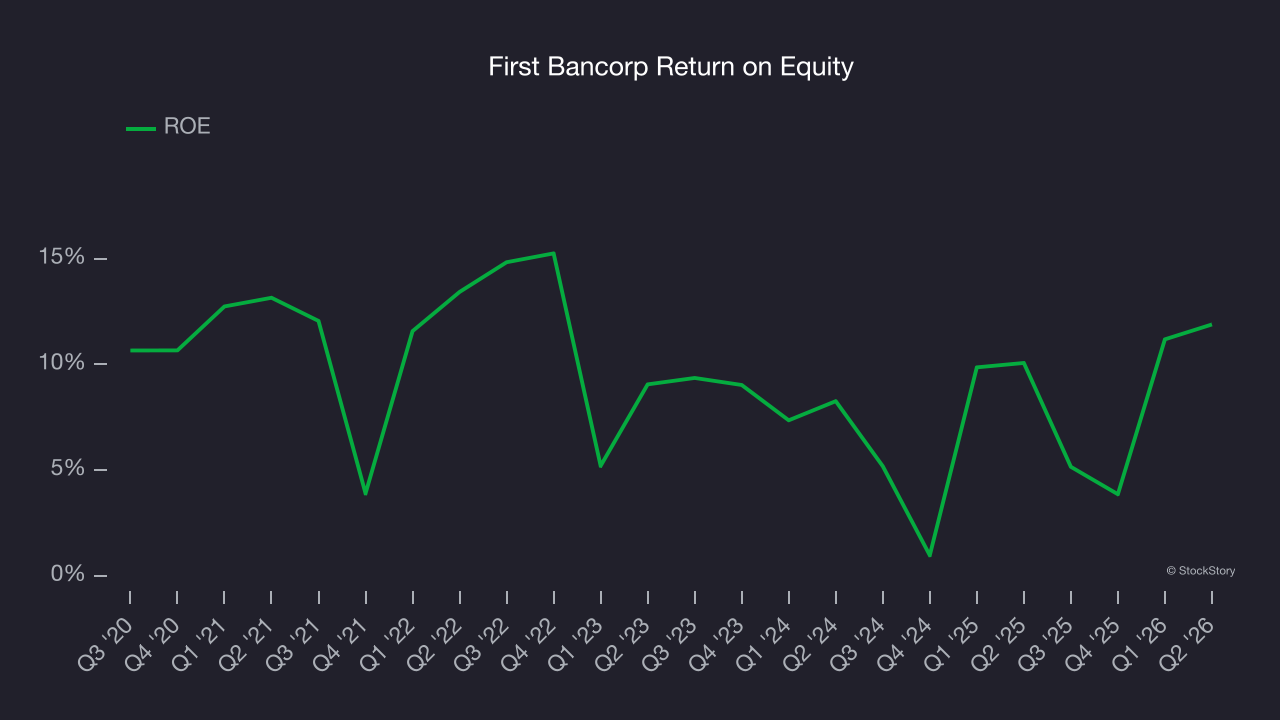
Over the last five years, First Bancorp has averaged an ROE of 8.9%, uninspiring for a company operating in a sector where the average shakes out around 10%.
Final Judgment
First Bancorp’s business quality ultimately falls short of our standards. With its shares underperforming the market lately, the stock trades at 1.4× forward P/B (or $59.25 per share). This valuation multiple is fair, but we don’t have much faith in the company. We’re pretty confident there are superior stocks to buy right now. We’d recommend looking at one of our all-time favorite software stocks.
Stocks We Would Buy Instead of First Bancorp
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.